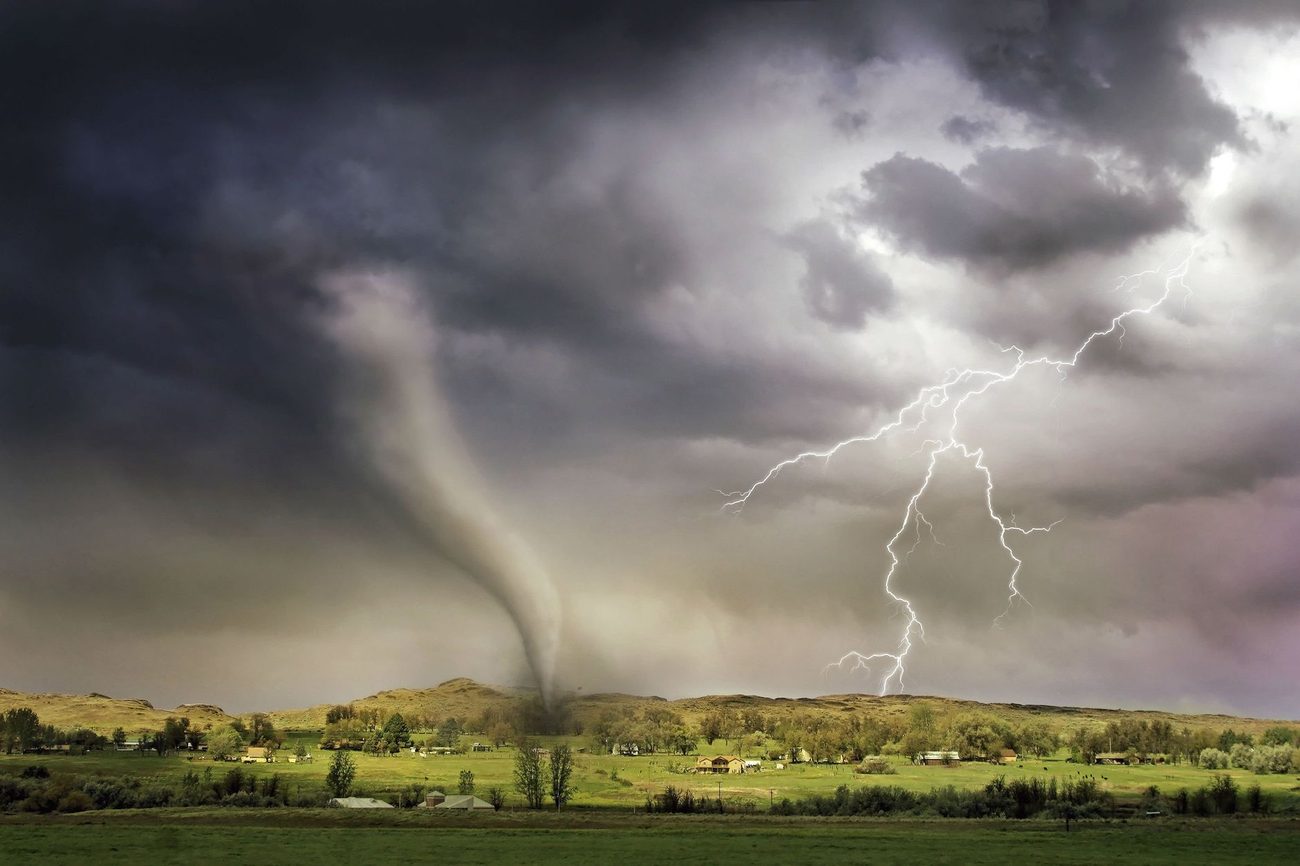
The weather radio went off at 1:40 in the morning earlier this month, that long tone that makes your heart jump before your brain catches up. Tornado warning for Macon County. Tyler grabbed Moose by the collar, I grabbed my phone and the flashlight, and the three of us sat in the bathroom for twenty-five minutes listening to rain hit the roof sideways.
Our side of the duplex doesn't have a basement. The bathroom is in the middle of the building with no outside walls, so that's our spot. Moose decided the tub was his, and honestly he looked more comfortable than we did.
The storm passed north of town. We lost a few shingles off the carport and Gloria's trash cart ended up in our yard. That was it. But I couldn't sleep afterward, and somewhere around three in the morning I started wondering what we'd do if it hadn't passed north. So the next weekend, we checked.
What we checked in our policies
I'm not an insurance agent. This is what we found in our own paperwork, with a couple of calls to our agent. Yours will be written differently, so read your own.
Renters insurance. Wind is one of the named causes our policy covers, and tornado damage counts as wind. If our belongings were destroyed, we'd be covered up to our $30,000 personal property limit at replacement cost, minus our $500 deductible. Loss of use would help pay for somewhere to live while things got sorted out. The building itself is Mr. Dale's to insure. The one thing I double-checked was flooding. It's not covered, even if the water comes from the same storm. Wind damage is in; rising water is out.
The cars. Hail, wind and a tree on the hood fall under comprehensive, not collision. That's one reason we left our comprehensive deductible at $500 when we raised collision to $1,000 in March. A hailstorm would probably hit both vehicles at once, so that's $500 each, $1,000 total. Our emergency fund can handle that.
Tyler's mowing equipment. His mower and trimmer live in the carport. Our agent told us renters policies often limit coverage on property used for a business, and ours has a lower limit for it. His gear is under that limit for now. If you have a side business, ask about this one, because keeping it in your carport doesn't make it household stuff.
Our life insurance. We bought term policies last month. I made sure we both know where the documents are and that the beneficiary names are spelled right.
Proof of what we own. Last spring I filmed every room for our renters inventory. I redid it this month and it took half the time. The video is on both our phones and saved online, so it doesn't depend on the duplex still standing. I also saved photos of both declarations pages and put our agent's after-hours claims number in both phones.
What's in the go-bag
The other thing I realized at three in the morning was that we didn't have a bag ready. Now we do. It's an old duffel in the hall closet, the one closest to the bathroom.
- Copies of our IDs, insurance cards and declarations pages in a zip-top bag
- Our agent's number and our policy numbers on an index card, in case the phones die
- The power bank we bought after the ice storm, charged, plus two cords
- A flashlight, a headlamp and spare batteries for the weather radio
- A week of my prescription (I work in a pharmacy, so I was not going to forget this one)
- Six bottles of water and a box of granola bars
- $100 in small bills, in an envelope
- A leash, a collapsible bowl and two days of Moose's food
- Sturdy shoes for each of us, because nobody wants to walk through broken glass in slippers
Most of it we already had. We spent $34 on what we didn't: the headlamp for $12, batteries for $9, the collapsible bowl for $5 and $8 for the water and granola bars. The $100 came out of our regular budget over two paychecks.
A few things I'll do differently from now on. I'll check the bag every spring when I redo the inventory video, swap out the water and the granola bars, and refill the prescription before it expires. I'll keep paper copies of the important numbers, because a dead phone can't call anyone. And I'll actually read the wind and flood sections of any policy we buy from here on, including the homeowners policy we'll need next.
If you have a free weekend this spring, find your declarations pages and read the parts about wind, flood and loss of use. Then pack a bag. It took us one Saturday afternoon and $34, which is a lot less than another night on a bathroom floor wondering.